Vittorio Iacovoni | New York - Milan
From numbers to decisions: finance and economics through a quantitative lens.
Level I Candidate in the CFA Program · Final-year master’s student
- M.S. Financial Technology & Analytics Stevens Institute of Technology, major in Financial Mathematics, Quantitative Finance & Financial Engineering program 2026 – 2027
- M.Sc. Economics, Management & Governance LIUC – Università Cattaneo, major in Banking & Finance 2025 – 2027
Dual-degree program between LIUC and Stevens
At a glance
- 110/110Expected final grade, M.Sc. in Banking & Finance, LIUC (Italian scale)
- 105/110B.Sc. in Business Economics, LIUC (Italian scale)
- PwCAudit Intern, Assurance, Mar – Jul 2025
- 90+Members of the Starting Finance Club LIUC, which I co-founded
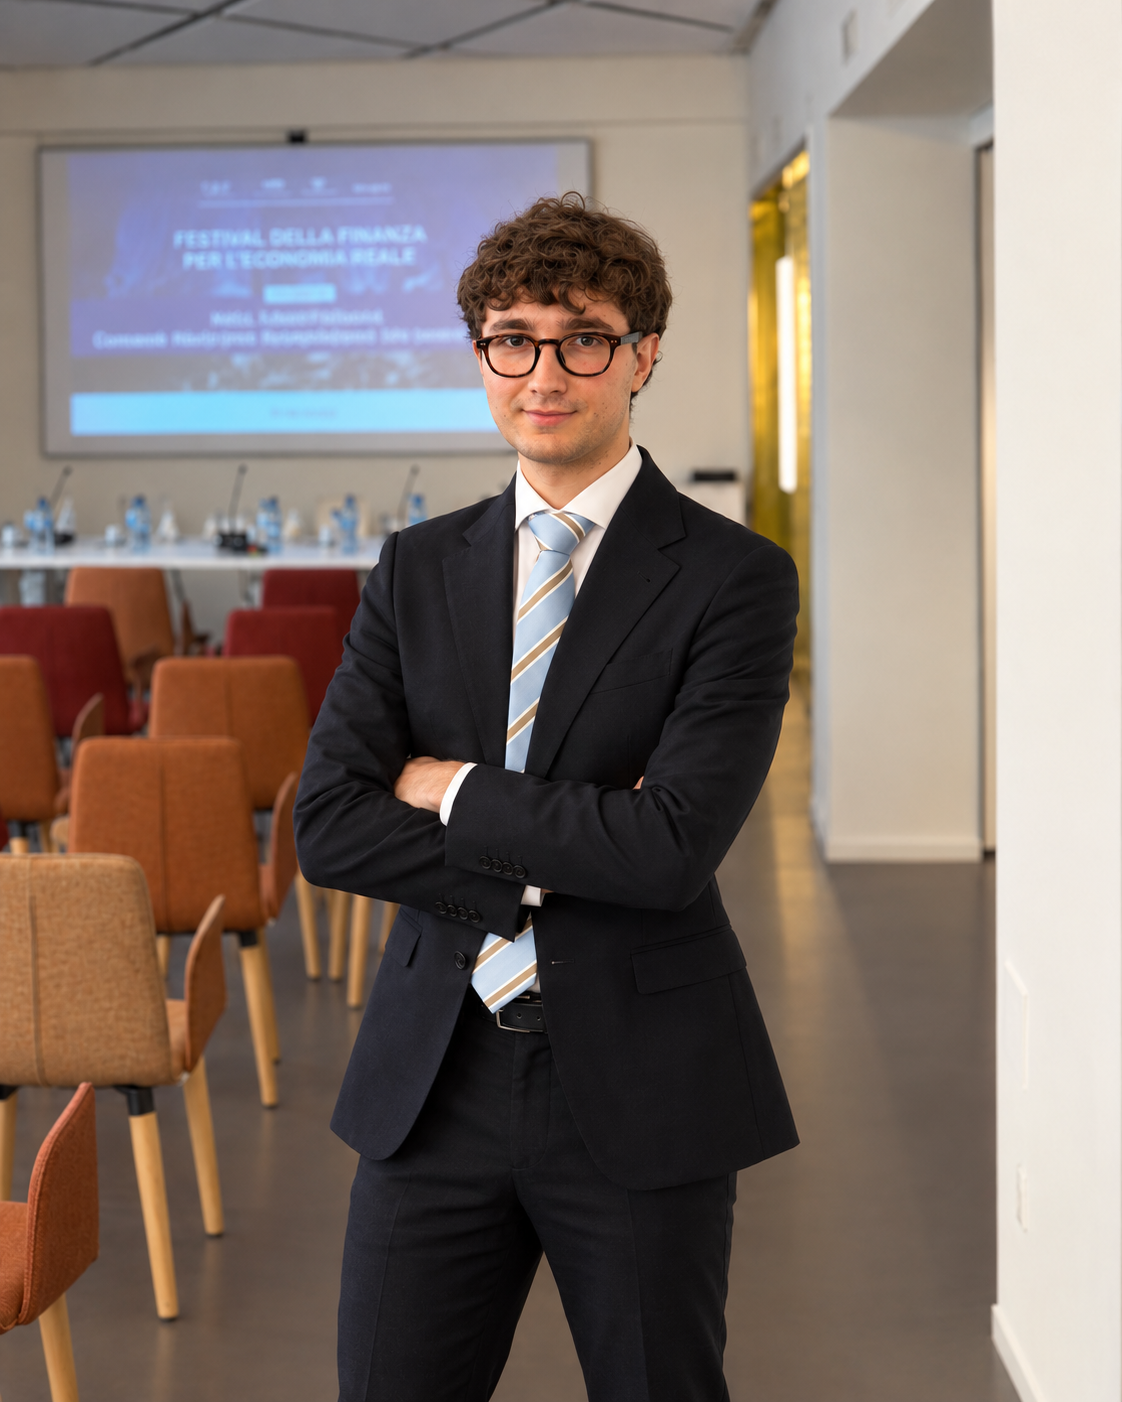
- Apr 2026Speaker at the Festival della Finanza, alongside JPMorgan, Equita SIM and Assolombarda
- BFF · BSABloomberg certifications
Track record
Full experience →-
Apr 2026
event
Speaker, Festival della Finanza
Spoke on the health of Italian public markets and trends in private banking, alongside professionals from JPMorgan, Equita SIM and Assolombarda.
-
2025 – present
elected role
Student Representative, LIUC
Elected to represent graduate students and advocate for improvements to academic programs.
-
Mar – Jul 2025
internship
PwC Italy, Audit Intern
Analytical procedures, reconciliations and internal control assessment across multiple Assurance clients, in line with ISA standards.
-
2023 – 2025
leadership
Starting Finance Club LIUC, Co-Founder & Vice President
University finance club with 90+ members: industry speaker events, investment competitions and analytical articles for VareseNews.
-
2022 – 2025
105/110
LIUC, B.Sc. in Business Economics
Accounting and financial reporting, financial mathematics, advanced statistics. Academic exchange at Toulouse School of Management.
Focus areas
View projects →AI for private banking
Using AI to understand each client’s profile in depth and build portfolios tailored to their goals, time horizon and risk tolerance.
client profiling, machine learningQuantitative models
Monte Carlo simulation, geometric Brownian motion, backtesting of algorithmic strategies and statistical analysis of market data.
Python, SQL, R, VBAAsset management & allocation
Portfolio optimization with the efficient frontier, the Single-Index Model and beta shrinkage, through to GMV and tangency portfolios.
Elton–Gruber, MarkowitzEquity research
Financial statement analysis, company valuation and building an investment thesis, from the numbers to the recommendation.
Bloomberg, ExcelDerivatives
Option pricing with Black–Scholes and Garman–Kohlhagen, volatility surfaces, implied volatility and zero-cost collar strategies.
Bloomberg OVML conventionsRisk management
Value at Risk, sensitivities through the Greeks, and a working view of internal controls from my audit experience.
VaR, Greeks, internal controlsContact
- Resume
Curiosity creates the future.
More about me